Is F&O Income Business Income? Here’s What You Need to Know
Futures and Options (F&O) trading is gaining popularity in India, but many traders are unsure about its tax treatment or mistakenly believe it need not be reported in their Income Tax Return (ITR).
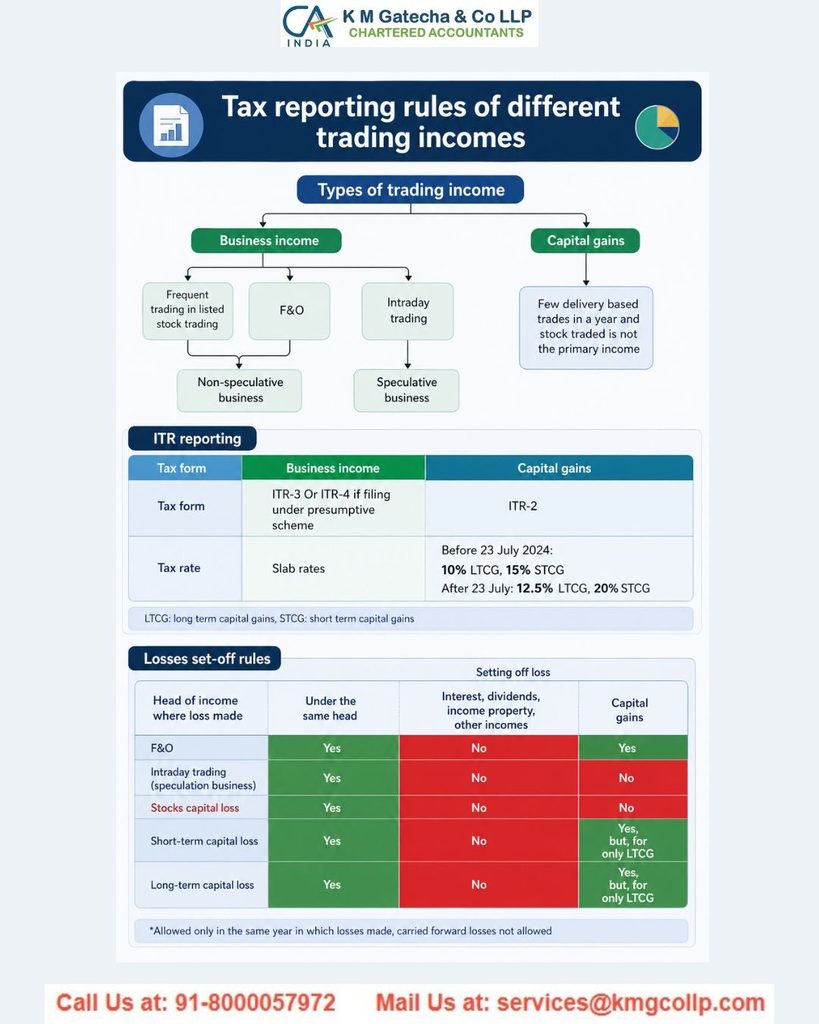
A common question is whether F&O income is treated as capital gains or business income. As per the Income Tax Act, F&O trading is classified as non-speculative business income, meaning all profits and losses must be reported under “Income from Business & Profession.”
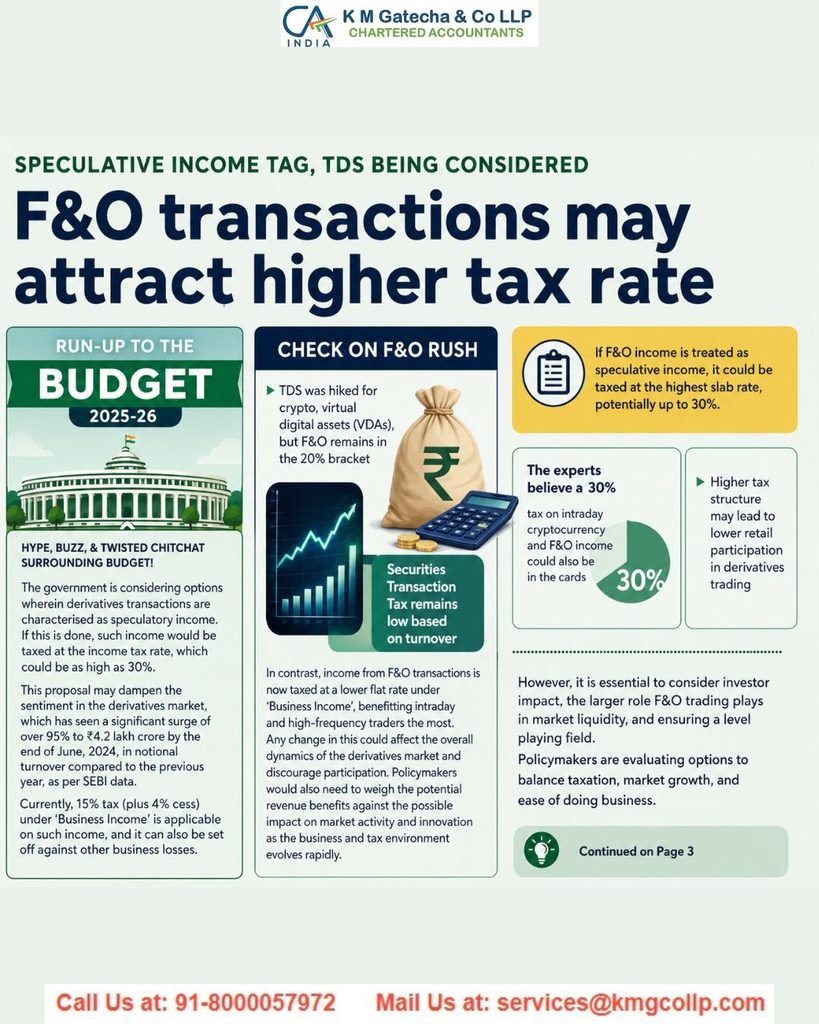
Budget 2026 Updates
- Share buybacks will be taxed as capital gains for all shareholders
- Promoters will be liable for additional buyback tax
These changes will apply from FY 2026-27.
Income Tax Act 2025 Update
The terms “Previous Year” and “Assessment Year” have been replaced with “Tax Year.” For instance, income earned in 2025-26 will be referred to as Tax Year 2025-26. However, FY and AY are still commonly used for clarity.
Is F&O Income Capital Gain or Business Income?
Under Section 43(5), F&O trading is treated as business income. Even if you incur losses, you are still required to file an ITR and report such transactions. Not reporting them may lead to notices from the tax department.
How to Calculate F&O Income
Income is calculated by adding the absolute value of all profits and losses.
For example:
Loss ₹10,000 + Profit ₹20,000 = Turnover ₹30,000
Expenses Allowed as Deductions
You can claim business-related expenses such as:
- Brokerage charges
- Internet and phone bills
- Advisory or consultancy fees
- Software subscriptions
- Employee or support costs
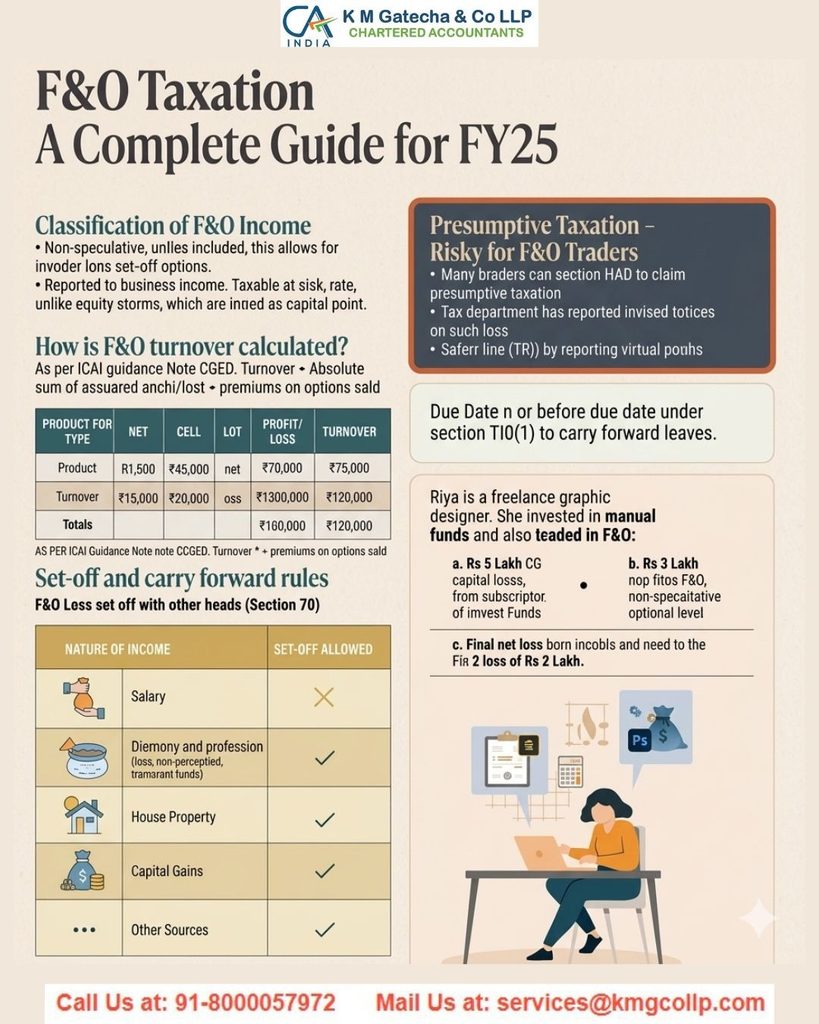
Set-Off and Carry Forward of Losses
F&O losses can be adjusted against any income except salary.
Unadjusted losses can be carried forward for up to 8 years.
Where to Report F&O Income
- ITR-3: For regular business income
- ITR-4: If opting for presumptive taxation
Profits are taxed as per slab rates, while losses can be set off or carried forward.
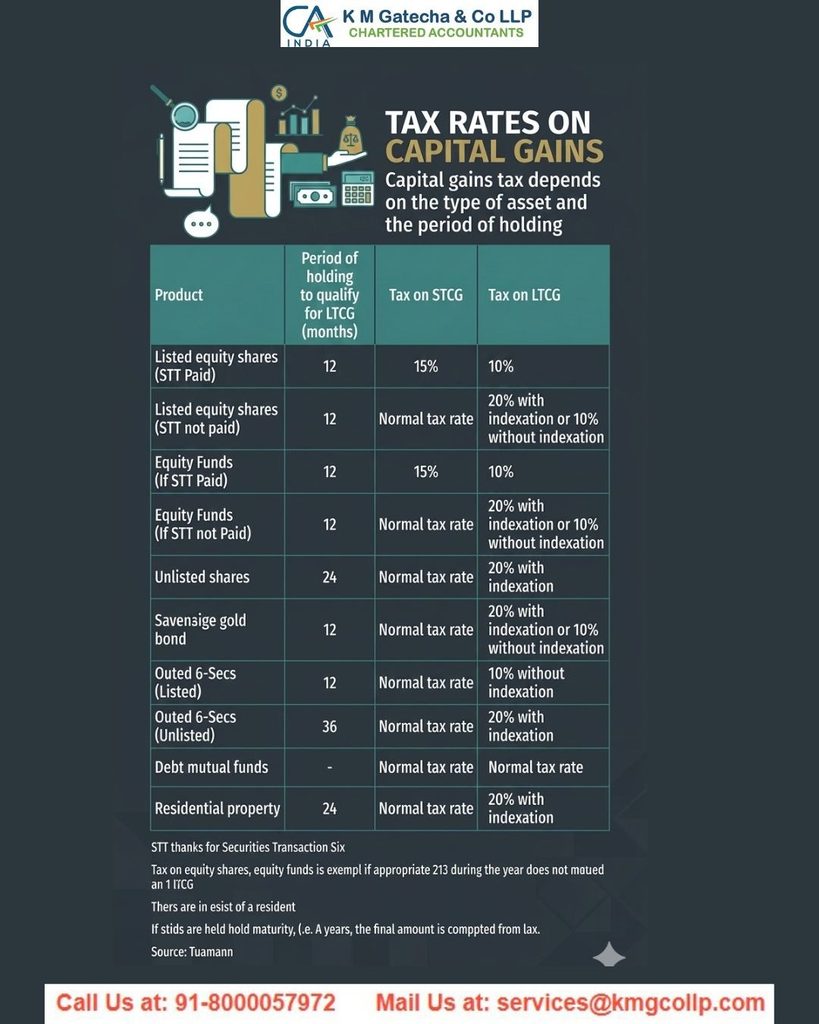
Books of Accounts Requirement
Maintaining books is mandatory if:
- Income exceeds ₹2.5 lakh, or
- Turnover exceeds ₹25 lakh in any of the last 3 years
Proper records like trading statements, bank statements, and expense proofs must be maintained.
Tax Audit Applicability (Section 44AB)
- Up to ₹3 crore turnover: Audit required if profit is below 6% and presumptive scheme not opted
- ₹3 crore to ₹10 crore: No audit if 95% transactions are digital
- Above ₹10 crore: Audit is compulsory
Final Note
F&O trading is treated as a business activity, so both profits and losses must be reported in your ITR. Understanding these rules is important to avoid penalties and ensure proper compliance.
Disclaimer: The content on this website is for informational purposes only and does not constitute legal, financial, or professional advice. Please consult qualified experts before acting on any information. K M GATECHA & CO LLP accepts no liability for errors, omissions, or outcomes from the use of this content. This site is not an advertisement or solicitation.
Need Help?
FAQs
Which ITR form is suitable for reporting income from F&O trading in India?
Income from Futures and Options (F&O) trading is treated as business income under the Income Tax Act. Therefore, it should be reported in ITR-3 for individuals maintaining regular books of accounts or ITR-4 if opting for the presumptive taxation scheme under Section 44AD, subject to eligibility conditions.
How is F&O trading income taxed in India?
F&O trading income is taxed as business income and added to your total income for the year. The tax is calculated according to the applicable income tax slab rates. A tax audit may be required depending on turnover, profit percentage, and whether the presumptive taxation scheme is opted for.
How do I show F&O transactions in my Income Tax Return (ITR)?
F&O transactions should be reported under the head “Profits and Gains from Business or Profession” in the relevant ITR form. You must disclose turnover, profit or loss, and related business expenses. Both profits and losses must be reported, even if there is no tax payable.
How much tax is payable on options trading income?
Income from options trading is treated as non-speculative business income and taxed according to the applicable income tax slab rates. Securities Transaction Tax (STT) is also applicable on options transactions as per stock exchange regulations.
Is there any tax on intraday trading?
Yes, intraday trading is treated as speculative business income. Profits from intraday trading are taxed as business income, and losses are classified as speculative losses, which can be carried forward for up to four years subject to tax filing compliance.
Can F&O losses be set off against capital gains?
Yes, F&O losses are considered non-speculative business losses and can be set off against other income such as business income, capital gains, rental income, or interest income. However, these losses cannot be set off against salary income.
What is F&O turnover for income tax purposes?
F&O turnover refers to the total of absolute profits and losses from all F&O transactions during the financial year. This turnover is used to determine tax audit requirements and eligibility for the presumptive taxation scheme.
How can I reduce my tax liability on F&O trading?
You can reduce your tax liability by claiming eligible business expenses such as brokerage charges, internet expenses, software subscriptions, advisory fees, and depreciation on equipment used for trading. Proper record-keeping and tax planning can help optimize tax liability.
Can I skip reporting F&O losses in my Income Tax Return?
No, you cannot skip reporting F&O losses. All trading losses must be reported in your Income Tax Return. Reporting losses allows you to carry them forward for up to eight assessment years and set them off against future business income.
How should futures trading be reported for income tax purposes?
Futures trading should be reported as business income in ITR-3 or ITR-4, depending on whether the taxpayer opts for the presumptive taxation scheme and meets the eligibility criteria.
Table of Contents
Toggle