

Practical HUF Tax Planning, PAN Registration and Compliance Guide
A Hindu Undivided Family (HUF) can be a separate taxable person under Indian income tax law. However, simply obtaining a separate PAN or opening an HUF bank account does not automatically create additional tax savings.
The actual tax treatment depends on the legal ownership of assets, the source of funds, whether income belongs to the HUF or its members, applicable clubbing provisions and the tax regime selected.
K M GATECHA & CO LLP, Chartered Accountants, provides professional assistance with HUF formation documentation, PAN applications, income tax returns, property-related taxation, family asset structuring and HUF partition matters.
HUF Formation vs HUF Registration: What Is the Difference?
A HUF generally derives its existence from the applicable personal law and family relationship. It is not incorporated or registered in the same way as a private limited company or LLP.
For tax and banking purposes, an eligible HUF may require a separate PAN, appropriate declarations, identification of the Karta and relevant supporting documents.
A written HUF deed may help document the name of the HUF, the Karta, members, family assets and operational arrangements. However, execution of a deed by itself does not establish that individually owned property has legally become HUF property.
How to Apply for an HUF PAN Card in India
A HUF requires its own PAN for separately reporting its taxable income and carrying out relevant financial transactions.
The usual documentation process involves:
-
Determining the legal existence and particulars of the HUF.
-
Identifying the Karta and relevant family members.
-
Preparing the declaration or affidavit required for the PAN application.
-
Collecting identity, address and date-of-birth evidence of the Karta as prescribed.
-
Submitting the applicable PAN application.
-
Completing the verification requirements.
-
Opening a bank account in the HUF’s name, subject to the bank’s KYC requirements.
The PAN application process should be completed using the current requirements of the authorised PAN service provider.
HUF Income vs Individual Income: Which Income Belongs to Whom?
A major issue in HUF tax planning is determining whether income legally belongs to the family entity or an individual member.
Income generated from property or investments genuinely belonging to the HUF may constitute HUF income.
However, income arising from an individual’s personal services, salary or separately owned assets generally cannot be assigned to the HUF merely to reduce tax.
For example, where ancestral property is legally owned by an HUF and produces rental income, the rental income may be assessable in the hands of the HUF.
Conversely, where a salaried individual owns a property personally, merely directing the rent to an HUF bank account does not automatically make the rent taxable as HUF income.
The substance and legal ownership of the income-producing asset must be established.
Can an Individual Transfer Personal Property to an HUF to Save Tax?
Transferring individually owned property to an HUF does not necessarily produce tax savings.
Under the applicable clubbing provisions, including section 64(2) of the Income-tax Act, 1961 for relevant earlier periods, income from property transferred by a member to an HUF without adequate consideration may remain taxable in the hands of the transferring individual.
This principle is important where taxpayers attempt to transfer self-acquired investments, residential property or income-producing assets into an HUF solely for tax planning.
Before transferring assets, the following matters should be examined:
-
Existing legal ownership.
-
Source of acquisition funds.
-
Nature and consideration of the transfer.
-
Applicability of clubbing provisions.
-
Capital gains and stamp duty consequences.
-
Subsequent income and distribution treatment.
-
Rights of other HUF members.
HUF Taxation Under the Old and New Tax Regimes
A HUF is recognised as a separate taxable person and may be eligible for the applicable slab rates and deductions, subject to the relevant tax regime.
Under the old tax regime, eligible deductions may include specified investments and payments under provisions such as section 80C and health insurance deductions under section 80D, subject to the applicable conditions.
The new tax regime restricts several deductions that may otherwise be available under the old regime.
Therefore, a HUF should not automatically select the old regime merely because it holds investments or owns property.
A tax comparison should consider taxable income, eligible deductions, business income, applicable regime-selection restrictions and other relevant circumstances.
Can a HUF Own Property and Receive Rental Income?
Yes. A HUF may own immovable property, subject to the applicable legal requirements.
Property may become HUF property through legally recognised modes, including certain inheritances, family arrangements and acquisitions using existing HUF funds.
Income and capital gains relating to such property must be reported according to the actual ownership and applicable tax provisions.
Where property ownership is disputed or documents show an individual owner, the mere use of an HUF PAN does not establish HUF ownership.
Can a Daughter Become Karta of a HUF?
Daughters have coparcenary rights under the Hindu Succession Act, 1956, as amended in 2005.
The possibility of a daughter acting as Karta should be considered in light of her coparcenary status, seniority, applicable personal law and relevant judicial decisions.
A female coparcener is not disqualified merely because she is a woman.
HUF Partition and Income Tax Consequences
Partition of an HUF involves important legal and tax considerations.
A total partition involves division of the relevant joint family property among the persons entitled to it.
For income tax purposes, recognition of partition may require compliance with statutory conditions and assessment procedures.
Partial partitions effected after the statutory cut-off are generally not recognised for income tax purposes under the restrictions contained in the applicable law.
Important considerations include:
-
Identification and valuation of HUF assets.
-
Rights and entitlements of family members.
-
Treatment of outstanding liabilities.
-
Documentation of asset distribution.
-
Stamp duty and registration implications.
-
Income tax recognition of partition.
-
Subsequent taxation of the assets received.
A partition deed should reflect the actual family arrangement and should not be treated merely as a tax-saving instrument.
Common Mistakes in HUF Tax Planning
Taxpayers should avoid the following mistakes:
-
Treating an HUF PAN as proof of HUF ownership.
-
Transferring personal salary income into the HUF’s return.
-
Ignoring clubbing provisions.
-
Assuming all gifts to an HUF are exempt.
-
Claiming deductions without checking the applicable tax regime.
-
Reporting an individually owned property as HUF property without supporting evidence.
-
Assuming all HUF partitions are automatically recognised for income tax purposes.
-
Mixing the personal bank transactions of the Karta with HUF transactions.
-
Distributing income or assets without evaluating legal ownership and tax consequences.
Proper source-of-funds documentation, ownership records and separate books or transaction records can help establish the basis of HUF income tax reporting.
Chartered Accountant Assistance for HUF Formation and Tax Filing
K M GATECHA & CO LLP provides HUF-related professional services, including:
-
HUF formation documentation.
-
HUF declaration and deed preparation assistance.
-
HUF PAN application support.
-
HUF income tax return preparation and filing.
-
Separate HUF income computation.
-
Old and new tax regime comparison.
-
HUF property income taxation.
-
Capital gains computation for HUF assets.
-
HUF investment and bank transaction review.
-
Clubbing-of-income analysis.
-
Family settlement tax advisory.
-
HUF partition and dissolution-related tax documentation.
-
Income tax notice replies involving HUF transactions.
K M GATECHA & CO LLP – Chartered Accountants
Website: https://kmgcollp.com/
Email: services@kmgcollp.com
Phone: +91 8000057972
What is a Hindu Undivided Family (HUF)? Features & Tax Benefits
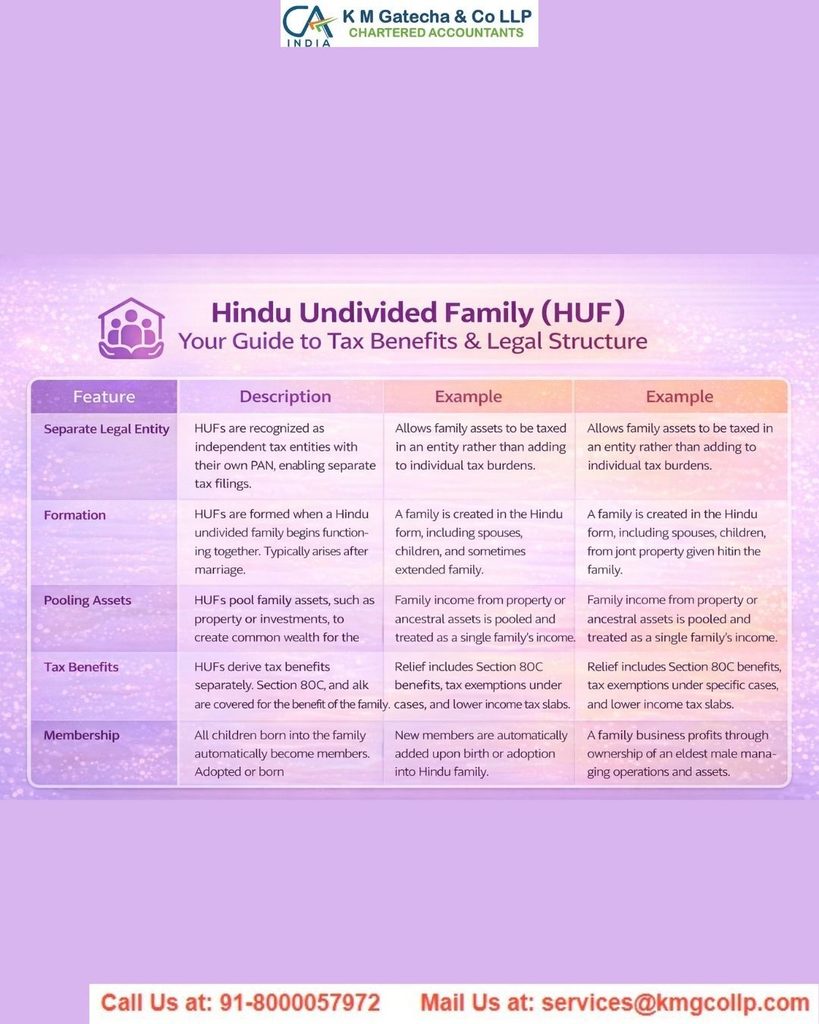
HUF stands for Hindu Undivided Family. It is treated as a separate legal entity under the Income Tax Act and is mainly created to help families manage income and save taxes. According to Hindu law, a HUF consists of individuals descended from a common ancestor, including their wives and unmarried daughters. The HUF is usually managed by the eldest family member, known as the Karta.
Income Tax Act 2025 Update
The Income Tax Act, 2025 has replaced the terms “Previous Year” and “Assessment Year” with “Tax Year.” For example, income earned during 2025-26 will now be referred to as Tax Year 2025-26. However, since taxpayers are more familiar with the terms FY and AY, this guide continues to use them for easier understanding.
The new Act has also simplified and renumbered several sections and schedules.
What is a HUF?
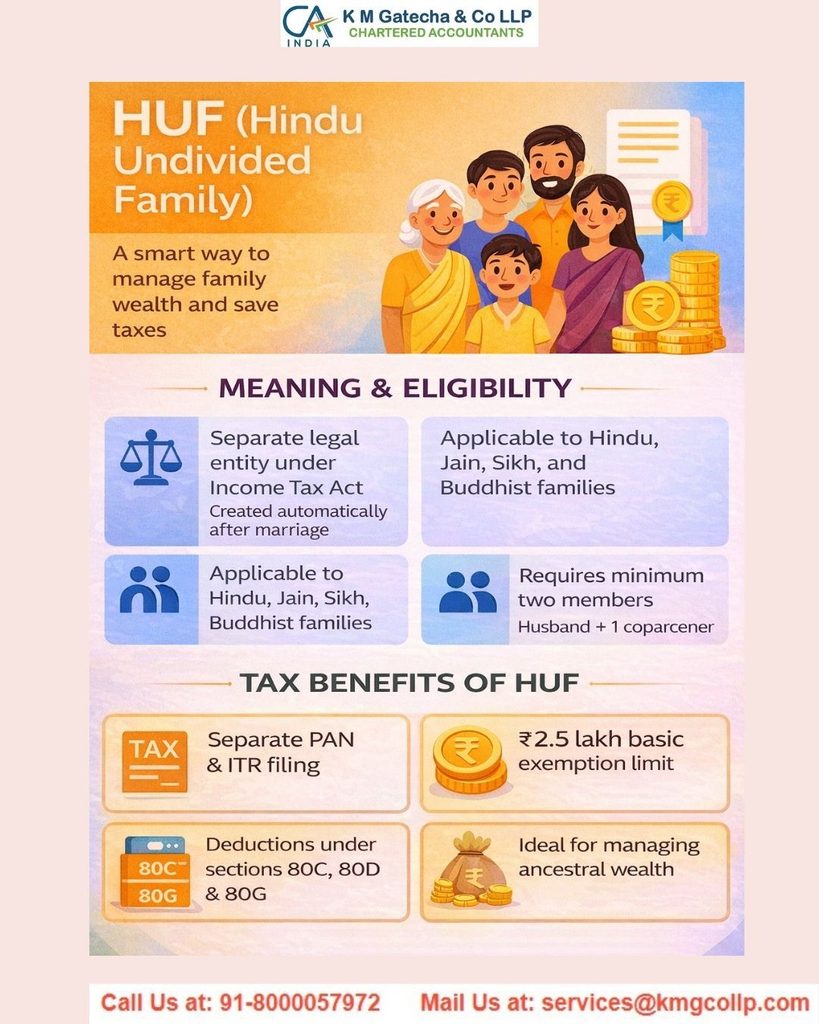
A Hindu Undivided Family is a joint family arrangement recognised as a separate taxable entity. It is generally formed when a family owns ancestral property, receives gifts, or acquires assets using joint family funds. Members of a HUF include descendants of a common ancestor, their spouses, and children.
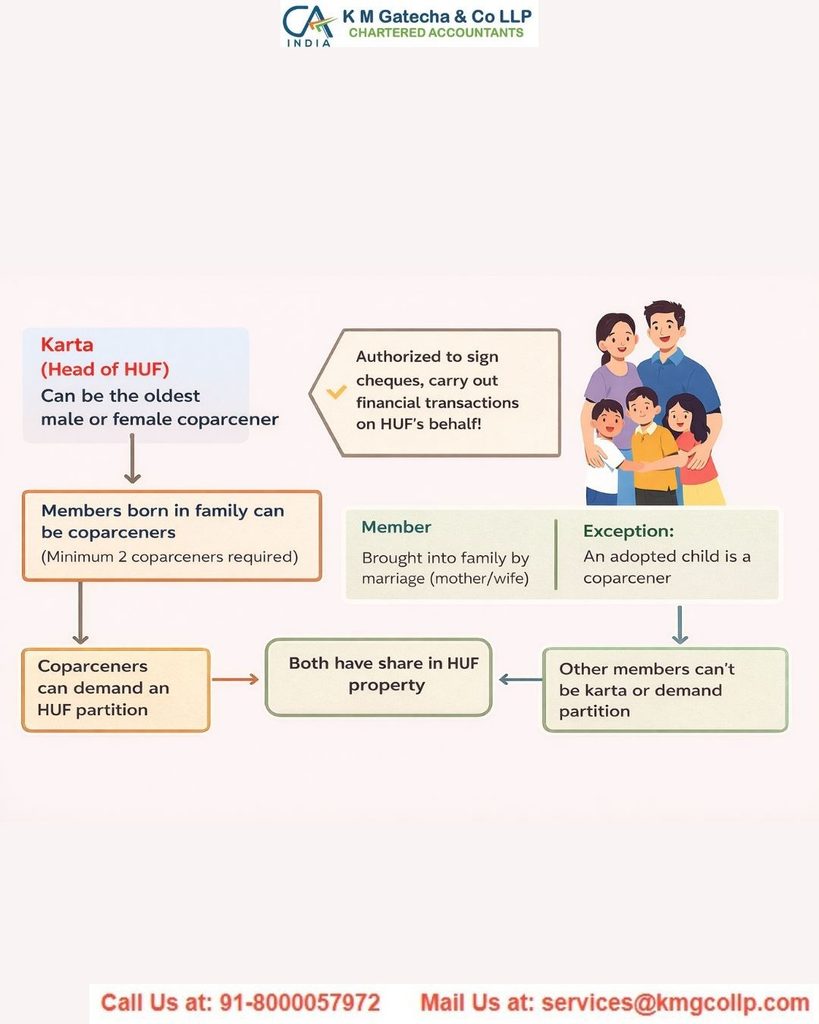
Under Section 2(31) of the Income Tax Act, a HUF is treated as a separate “person” for tax purposes. The head of the HUF is called the Karta, who manages the affairs and finances of the family. Male members are called coparceners, while female members are referred to as members. Today, even daughters can become Karta if they are the eldest member of the family.
Jains, Sikhs, and Buddhists are also eligible to form a HUF, even though they are not governed by Hindu law.
Rules for Forming a HUF
The following conditions must be fulfilled to create a HUF:
- A single person cannot form a HUF; a family is required.
- Marriage automatically creates a HUF.
- A HUF includes descendants of a common ancestor, their wives, and unmarried daughters.
- Hindus, Sikhs, Jains, and Buddhists can form a HUF.
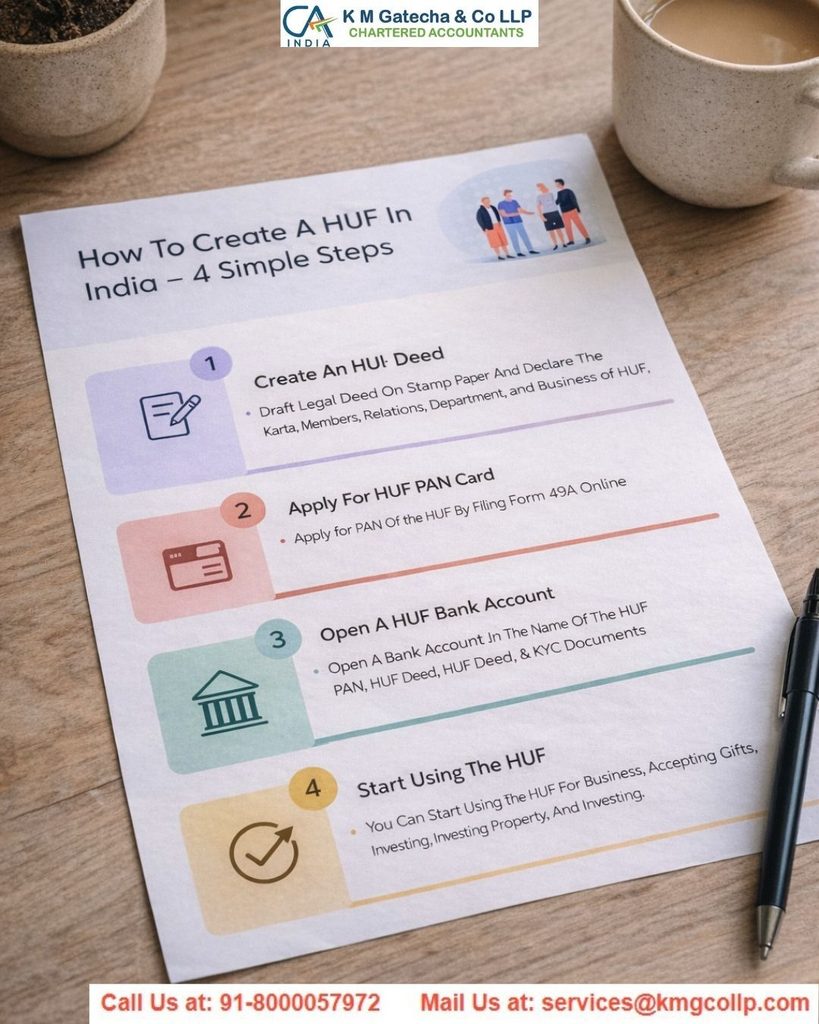
- The HUF must obtain a PAN card and open a separate bank account.
- A formal HUF deed mentioning members and business details should be prepared.
- Members may contribute income or assets to the HUF corpus.
- The HUF can claim tax deductions and exemptions separately.
Tax Benefits of a HUF
A HUF enjoys separate tax treatment and receives many of the same deductions available to individuals.
Separate Tax Entity
A HUF has its own PAN card and files a separate income tax return. This allows the family to claim an additional basic exemption limit and reduce overall tax liability.
Tax Benefits under Section 80C
A HUF can claim deductions up to Rs.1.5 lakh under Section 80C for investments such as:
- ELSS
- PPF
- Life insurance premiums
- Tax-saving deposits
Health Insurance Deduction
A HUF can claim deduction under Section 80D for health insurance premiums paid for family members, providing an additional tax-saving benefit.
Residential Property Benefits
A HUF can own residential property in its own name. This helps families manage multiple properties and optimize taxation on house property income.
Investment and Business Income
The HUF can earn income from:
- Rental properties
- Business activities
- Investments in shares and mutual funds
- Interest income
Such income is taxed separately in the hands of the HUF.
Computation of HUF Income
The income of a HUF is calculated under different heads of income after excluding exempt income. Some important points include:
- Salary or remuneration earned by a member for personal services is treated as individual income.
- Income generated due to HUF investments may be treated as HUF income.
- Genuine remuneration paid by the HUF to members for services rendered can be claimed as an expense.
The following are not taxed as HUF income:
- Personal income of members
- Income from self-acquired property transferred without consideration
- Income from a woman’s Stridhan
- Income from individual property of a daughter
Additional HUF Tax Advantages
Tax-Free Gifts
Gifts received by a HUF up to Rs.50,000 are tax-free. Certain larger gifts and property transfers may also qualify for exemption if structured properly.
Investment in Tax-Free Instruments
The HUF corpus can be invested in tax-saving and tax-free instruments. Income from these investments is taxed separately in the HUF’s hands.
Example of Tax Saving through HUF
Suppose a family earns income from salary, business, and ancestral property. By transferring rental income and part of the business income to the HUF, the family can divide taxable income across separate entities and reduce their overall tax burden significantly.
Disadvantages of Forming a HUF
Despite the tax benefits, a HUF also has certain limitations:
- All members have equal rights over HUF assets.
- Selling HUF property requires consent from members.
- Family disputes may create complications.
- Dissolving a HUF can be legally difficult.
- The relevance of HUFs has reduced with the rise of nuclear families.
Ways to Reduce Tax Liability through HUF
Rental Income
Rental income from family-owned property can be taxed under the HUF.
Business Income
Family businesses operated under the HUF structure can reduce overall tax liability.
Remuneration to Members
Payments made to the Karta or members for genuine services can be claimed as deductions.
Family Arrangements
Family settlements are generally not treated as transfers and may not attract tax.
Can a HUF Hold Property?
Yes, a HUF can own assets in its own name. Common assets include:
- Ancestral property
- Gifts received by the HUF
- Property purchased using joint family funds
- Assets received through a will
Since the assets belong collectively to the family, their transfer requires approval from all members.
Partition of a HUF
A HUF can be divided through partition:
Total Partition
All assets are distributed among members, and the HUF ceases to exist.
Partial Partition
Only certain members or specific assets are separated while the remaining HUF continues.
Important Points about HUF
- A HUF must file income tax returns separately every year.
- Clubbing provisions may apply if property is transferred to the HUF without consideration.
- Female members can become Karta in the absence of a male member.
- Managing large HUFs can become complicated due to growing family size and disputes.
A Hindu Undivided Family offers several tax-saving opportunities through separate taxation, deductions, and income distribution. However, families should also consider the legal and practical challenges before creating a HUF structure.
Disclaimer: The content on this website is for informational purposes only and does not constitute legal, financial, or professional advice. Please consult qualified experts before acting on any information. K M GATECHA & CO LLP accepts no liability for errors, omissions, or outcomes from the use of this content. This site is not an advertisement or solicitation.


